
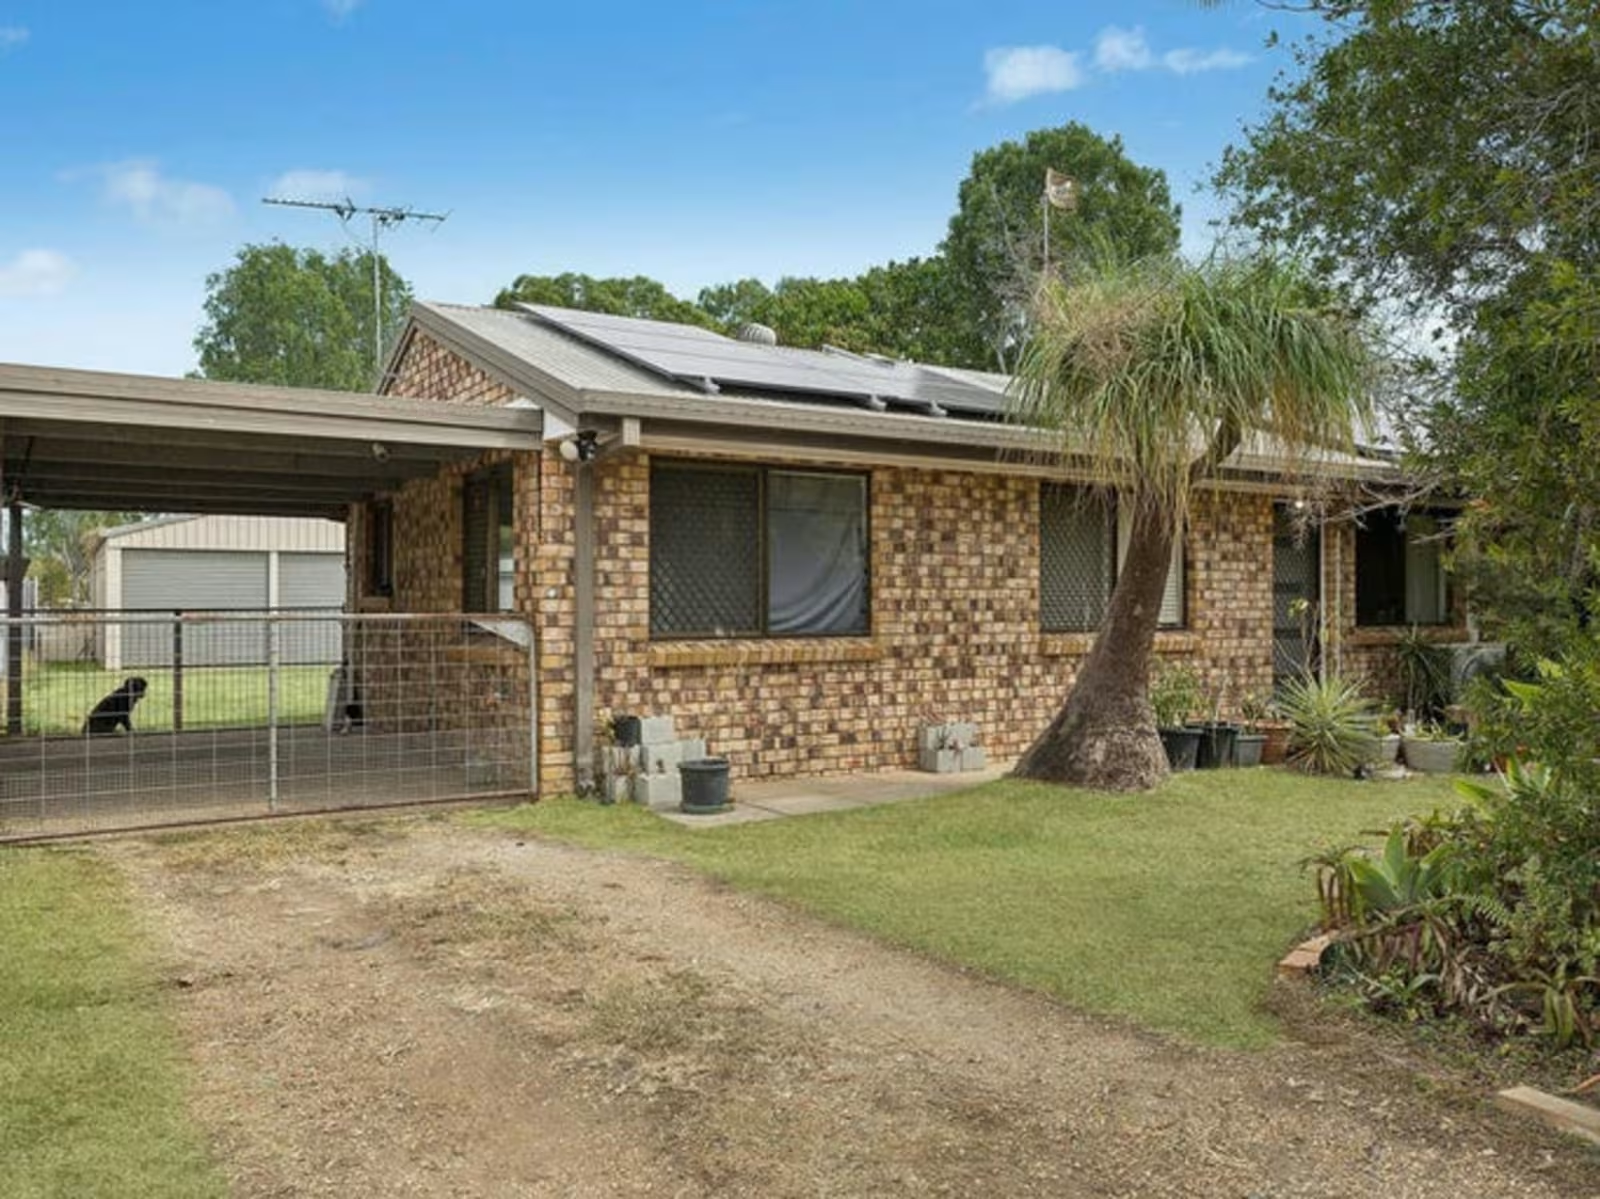
Can you buy a home with no deposit in Australia?
Not with a standard home loan. Lenders generally want a deposit of at least 5%, and they only accept that under a government scheme or when you pay Lenders Mortgage Insurance (LMI) on top of stamp duty and buying costs. However, other options let you move in with no deposit of your own, such as 0% deposit rent-to-own homes, where you build the deposit while you live in the home.
What are your options with no deposit or a low deposit?
There are six realistic routes. Here is what each one costs upfront on a $750,000 home, which sits in the typical range for a Queensland or New South Wales house.
- 20% deposit$163,925
- 10% deposit with LMIAbout $102,925
- 5% deposit with LMIAbout $83,425
- 5% Deposit Scheme$51,425
- Help to Buy$28,925
- Rent-to-own$8,000–$15,000
| Deposit | Stamp duty | Other costs | LMI | Total upfront | |
|---|---|---|---|---|---|
| 20% deposit | $150,000 | $10,925 | $3,000 | $0 | $163,925 |
| 10% deposit with LMI | $75,000 | $10,925 | $3,000 | About $14,000 | About $102,925 |
| 5% deposit with LMI | $37,500 | $10,925 | $3,000 | About $32,000 | About $83,425 |
| 5% Deposit Scheme | $37,500 | $10,925 | $3,000 | $0 | $51,425 |
| Help to Buy | $15,000 | $10,925 | $3,000 | $0 | $28,925 |
| Rent-to-own | $0 | $0 until you buy | $8,000–$15,000 | $0 | $8,000–$15,000 |
Saving the full 20%
A 20% deposit avoids LMI and gives you the widest choice of lenders. It is the cheapest way to buy if you can get there. The cost is time: while you save, you keep paying rent and prices keep moving.
A 5% or 10% deposit with LMI
Most lenders will go to a 90% or 95% loan if you pay LMI. The insurance protects the lender, not you, and it is usually added to your loan, so you pay interest on it for the life of the mortgage. On a $750,000 home it is roughly $14,000 with a 10% deposit and $32,000 with 5%.
Some lenders also offer deposit-assist loans, which lend you the deposit itself as a second loan. They get you in sooner, but the second loan usually carries a higher interest rate than a standard mortgage, and you carry two debts on one home. Check the rate, fees and repayment terms closely before signing.
The 5% Deposit Scheme
The Australian Government 5% Deposit Scheme lets first home buyers buy with a 5% deposit, or 2% for single parents and legal guardians, with no LMI. Since 1 October 2025 there are no income caps and no limit on places.
It is limited in other ways. You must be a first home buyer, or not have owned property in the last 10 years, and an Australian citizen or permanent resident. You apply through a participating lender, and the home must sit under the price cap for its area:
- Queensland: $1,000,000 in Brisbane, the Gold Coast and the Sunshine Coast; $700,000 elsewhere.
- New South Wales: $1,500,000 in Sydney and the regional centres, including Newcastle, Lake Macquarie, Illawarra and the Central Coast; $800,000 elsewhere.
You still need the 5% in cash, plus stamp duty unless a first home concession applies, and a loan of about 95% of the price.
Help to Buy
Help to Buy is a shared equity scheme. You put in at least 2%, and the government contributes up to 30% of the price of an existing home or 40% of a new one, owning that share of your house.
Places are limited to 10,000 a year, and you apply through a small panel of participating lenders. You need to be an Australian citizen with a taxable income at or below $103,000, or $165,000 for joint applicants and single parents. The government's share is repaid at the home's value when you sell or buy it out, so it shares in any growth.
Rent-to-own
Rent-to-own is not a loan. An investor buys or holds the home you choose, you move in as the tenant, and you hold an option to buy it later. Part of your weekly payment builds your deposit.
How does rent-to-own work when you have no deposit?
An investor buys or holds the home you choose, and you move in with an option to buy it from them later. You pay market rent plus a fixed contribution equal to 50% of your first-year rent. The contributions become your deposit, and at any time in years 4 to 8 you can switch to a mortgage and buy the home, with your choice of lender.
With PublicSquare's Rent-to-Own program:
- Your rent is reviewed once a year, and increases are capped at 4% or the legal maximum, whichever is lower.
- Your contribution is fixed for the whole lease and never rises.
- Your purchase price is the higher of a contracted minimum or an independent valuation. The minimum grows by 8% a year if you buy in year 4, stepping down to 4% a year if you buy in year 8, well below the national long-term average of 6.8% a year for houses (CoreLogic, 1993–2018).
- The owner pays the rates, insurance and maintenance during the lease.
- If you can't get a mortgage in years 4 to 8, the Owner's Sell-Back Guarantee lets you request an open-market sale and receive your contributions back, less any shortfall.
How much deposit does rent-to-own build?
On a $750,000 home renting for $650 a week, the contribution is $325 a week, or $16,900 a year. By year 6 that is $101,400, about 9.5% of the contracted minimum price. By year 8 it is $135,200, about 13.2%.
- Year 46.6%
- Year 58.0%
- Year 69.5%
- Year 711.2%
- Year 813.2%
| Year you buy | Deposit built | Contracted minimum price | Deposit as a share of price |
|---|---|---|---|
| Year 4 | $67,600 | $1,020,367 | 6.6% |
| Year 5 | $84,500 | $1,051,914 | 8.0% |
| Year 6 | $101,400 | $1,063,889 | 9.5% |
| Year 7 | $118,300 | $1,055,325 | 11.2% |
| Year 8 | $135,200 | $1,026,427 | 13.2% |
To see your deposit grow year by year, use the Deposit Builder calculator.
What does rent-to-own cost upfront and each week?
No deposit, and limited additional costs. There is no stamp duty or LMI to start, because the owner-investor buys the home. You may pay these costs when you complete your purchase, typically in year 6, 7 or 8.
All up, budget $8,000 to $15,000 for moving into a rent-to-own home, including everything below plus moving costs. A new home from our building panel sits at the lower end, and rolling over a bond from your current rental brings it down further. These are costs most buyers face in some form:
- Setup fee: none if you choose a new home from our building panel. For an established home, or a builder outside the panel, it is 0.99% of the home's value including GST.
- Engagement fee: $1,100 including GST, paid during pre-approval. Refundable, less a $75 + GST processing fee, until the Agreement Between Buyer and Seller is issued.
- Legal costs: $1,100 for independent legal advice and signing.
- Bond: a fixed $2,000, usually less than the four weeks' rent a standard rental asks for.
- First two weeks: two weeks of rent and contributions, paid before you move in.
Each week on the example home you would pay $650 rent, a $325 contribution and a $33 support fee: $1,008 in total. About a third of that is your contribution, which is credited to you as your deposit when you buy.
For comparison, the 5% Deposit Scheme on the same home needs about $51,400 in cash on day one. Once you move in, the costs of owning (principal and interest repayments on a 95% loan, plus rates, insurance and maintenance) are likely to run a couple of hundred dollars or more a week above rent-to-own on the same home.
Which option is right for you?
- You have 20%: buy with a standard mortgage. It costs the least over time.
- You have 5% and the home is under the price cap: the 5% Deposit Scheme avoids LMI.
- You have 5–10% but don't qualify for the scheme: a high-LVR loan works, but price in the LMI.
- You're a citizen under the income limits and happy for the government to own a chunk of your home: Help to Buy needs just 2%, if you can get one of the places.
- You have steady income but no deposit, and plan to stay four years or more: rent-to-own homes let you move in now and switch to a mortgage when you're ready.
Rent-to-own is currently available for houses in Queensland and New South Wales, for applicants under 50 years old.
When is rent-to-own not the right choice?
Rent-to-own suits people who could service a mortgage but don't have the deposit. It is the wrong fit if any of these apply:
- You already have a 20% deposit. A standard mortgage now will usually cost you less.
- You may move within four years. The option to buy opens in year 4, so it suits people planning to stay.
- You can't see a path to a mortgage. You will need a lender to approve you when you buy. The years of on-time payments help, but no lender's decision can be guaranteed.
- You want the cheapest weekly housing cost. Your payment is market rent plus the contribution, so it is higher than renting the same home.
- You expect prices to fall. You pay at least the contracted minimum, so a falling market does not lower your price.
If you can't get finance in years 4 to 8, the Owner's Sell-Back Guarantee lets you request an open-market sale with three lender rejection letters, provided you are not in default. You pay a fixed $3,300 marketing fee and receive your contributions back, less any shortfall if the home sells below the minimum price.
Frequently asked questions
Not from mainstream lenders. They generally want at least a 5% deposit, with LMI or a government scheme. Products advertised as "no deposit" usually lend you the deposit as a second loan at a higher interest rate, so read the rate and fees closely.
Sources
- 1.First Home Buyers (Housing Australia) — Australian Government 5% Deposit Scheme
- 2.First Home Buyers — 5% Deposit Scheme property price caps
- 3.First Home Buyers — Australian Government Help to Buy Scheme
- 4.Queensland Revenue Office — first home concession
- 5.Cotality — Australia's housing affordability hits new lows (November 2025)
- 6.Aussie and CoreLogic — 25 Years of Housing Trends (national house values 6.8% a year, 1993–2018)
Written by
Founder & CEO
Licensed real estate agent
I started PublicSquare in 2021 to give homebuyers a real path to ownership without a deposit, and investors a stronger-cashflow alternative to a standard rental. I hold real estate licences in Queensland and New South Wales and personally review every property that enters the program.
Reviewed by
Property Lead
Licensed agent · Former mortgage broker
I was a mortgage broker before joining PublicSquare, so I look at every property and every purchase the way a lender would. I now lead the property side of the program, helping homebuyers from their first info session through to move-in, and working with our buyers agency team on each acquisition for our investors.
Read more about Rent-to-Own.
This article is general information only and does not take your personal circumstances into account. PublicSquare is a licensed real estate agency, not a financial adviser or credit provider. Consider seeking independent advice before making a decision.